More Australians than ever are taking control of their retirement savings by establishing their own self-managed super fund (SMSF). According to ATO statistics released for June 2026, the 2025/26 financial year saw a record 52,020 new SMSFs established, representing a 4.2% net increase to 680,301 funds, with approximately $1.1 trillion invested by SMSFs in assets (source: ato.gov.au).
Compared to industry and retail super funds, an SMSF gives you direct control of your super and greater investment options. However, if not established correctly, it can create serious legal and tax consequences that are difficult and costly to unwind.
This guide covers every step, from establishment through to ongoing compliance, designed to provide a general overview of what is involved.
Step 1: Do Your Research
A self-managed superannuation fund (SMSF) is a trust in its legal structure and is required to have trustees who are responsible for managing and administering the fund. SMSFs can be complex financial vehicles and thorough research and consideration must be conducted prior to making the decision to establish one. Poor planning and research may lead you to make a costly decision that you regret later down the track.
Other general considerations may include, but are not limited to:
- What assets to invest in
- Researching asset returns and comparing to your existing super fund provider
- Seeking professional advice from a licensed financial adviser registered with ASIC
- Weighing the costs versus benefits of having an SMSF, particularly for smaller superannuation balances
- Your responsibilities as an SMSF trustee and as a member
- Who will join the SMSF as members
- Time and costs involved
The ATO has several handy starter guides and education pieces to explain in-depth about what is involved with setting up and running a self-managed super fund: Before you start an SMSF.
Proposed changes (August 2026): On 19 August 2026, Assistant Treasurer Daniel Mulino announced a package of proposed SMSF consumer protection reforms at the National Press Club. Key proposals include mandatory trustee education (approximately 3 hours, based on the ATO's existing SMSF course) and a knowledge test before a new SMSF can be registered, plus a formal requirement to have a written investment strategy in place at the time of set-up. These are proposed changes only. No draft legislation has been released and no start date has been set. Read more at SMSF Adviser.
Step 2: Choose Your Trustee Structure
If you decide to proceed with setting up an SMSF, you must then decide its trustee structure. Trustees are responsible for ensuring the SMSF meets the sole purpose test of providing retirement benefits to members, have a fiduciary duty to the fund's members to ensure the fund remains compliant with all relevant laws, and fulfils all other trustee obligations. There are two options to choose from: (1) individual persons acting as trustees, or (2) a company acting as the sole trustee.
We have a comparison between these two options outlining a few of the key points of difference on our pricing page. The ATO also has a brief video overview comparing trustee structure options on their website.
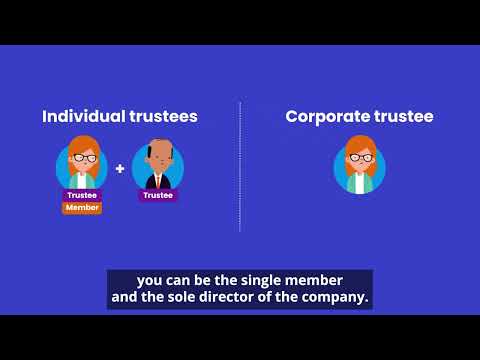
Source: ato.gov.au – Choose your SMSF trustee structure
Trustee eligibility and declaration
Before taking on the trustee or director role, each person must confirm they are eligible for the role:
- at least 18 years old
- not under a legal disability such as mental incapacity
- not a disqualified person. A disqualified person includes a person who has been convicted of dishonest offences, is bankrupt or insolvent, or may be a future risk to retirement savings.
Source: ato.gov.au – Appoint your SMSF trustees
Each trustee or director must also read and sign a trustee declaration within 21 days of appointment and retain it for at least 10 years.
Step 3: Create the Trust Deed
Once you have decided which trustee structure to proceed with, the next step is to organise the paperwork to establish the SMSF via a trust deed. A trust deed is the founding legal document which sets out the rules that govern how the SMSF will operate and covers matters such as: member provisions, contribution rules, benefit payment conditions, trustee powers, and winding up procedures.
In order to legally establish an SMSF, its trust deed must be prepared by a qualified legal provider, then signed and dated by all trustees. If a company is to act as the Trustee, legal documents must also be prepared and executed for it. For a complete overview, please refer to the following ATO guide: Create the trust deed.
Step 4: SMSF Registration with the ATO
Once the SMSF legal documents have been signed and dated, the SMSF must be registered with the ATO within 60 days. This involves 2 steps:
1. Complete Registration Process via ABR Website. An application must be lodged on behalf of the SMSF, and must also apply for its own Australian Business Number (ABN) and Tax File Number (TFN). These are usually issued instantly, however may take up to 28 business days if the ATO requires further checks. Outstanding tax lodgements and debt payments with the ATO are among the most common reasons for delays. The TFN must be issued before contributions can be received without withholding tax.
2. Regulated fund status. Once the application is assessed, the ATO will automatically determine and issue the fund's regulated status. This process is completed by the ATO and can take between 2 and 56 business days. A fund must hold regulated status to qualify as a complying fund and access the concessional 15% tax rate on earnings. If the ATO deems everything sufficient, they will issue a complying status, which will appear on the Super Fund Lookup website.
See the ATO's Register your SMSF guide for full details.
Don't Rush! ATO registration checks for a newly established SMSF can take anywhere from 2 to 56 business days. Until the fund has a complying status confirmed on the Super Fund Lookup website, it cannot receive rollovers from other funds. Entering into contractual arrangements to purchase assets before the ATO registration checks have been completed may create legal and compliance issues that are difficult and costly to resolve.
Step 5: Open a Dedicated Bank Account
Once the ATO has issued an ABN and TFN for the SMSF, it can then open its own bank account. An SMSF is required to hold a bank account in its name to ensure separation of fund assets from trustees' personal accounts. Most major Australian banks offer SMSF accounts. You will typically need to provide:
- The fund's ABN and TFN
- A certified copy of the trust deed
- Identity documents for all trustees / directors
- The corporate trustee's ACN (if applicable)
Step 6: Prepare an Investment Strategy
Every SMSF is required by law to have a written investment strategy tailored to the fund's members. The ATO's Create your SMSF investment strategy guide outlines four areas that must be addressed:
Risk & Return
Your risk tolerance and target returns relative to each member's retirement objectives.
Diversification
How the fund's assets will be spread across different asset classes.
Liquidity
Whether the fund can meet expenses and benefit payments as they fall due.
Insurance
Whether life, TPD, and income protection cover has been considered for each member.
A generic strategy won't cut it. Strategies that are too vague or clearly untailored to the fund are scrutinised by auditors. "The fund may invest in anything" is not a strategy. Outlining investment ranges of 0-100% across all asset classes is also not considered a tailored strategy. The strategy must be reviewed at least annually, or whenever circumstances change significantly.
Step 7: Roll Over Existing Super and Accept Contributions
Once an SMSF has an open bank account and a complying status showing on the Super Fund Lookup website, it is eligible to receive rollovers from external superannuation funds and contributions from members and their employers.
Superannuation held in an SMSF remains preserved until a condition of release is met (e.g. turning age 65). Early access to superannuation is illegal.
Rolling over from an existing fund
Rollovers are processed electronically via SuperStream. Your existing fund needs the SMSF's ABN, bank account details, and an Electronic Service Address (ESA), which allows the fund to receive SuperStream messages. A qualified SMSF accountant can assist with this process.
Before You Rollover. Check if you have active insurance policies (e.g. life insurance, TPD cover, income protection) with your existing superannuation fund provider if you intend to rollover your entire member balance, as the insurance policy may be cancelled after rolling over the funds and you may be left uncovered.
Directing employer contributions (SG)
Complete a Standard Choice Form (NAT 13080) and give it to your employer to direct Superannuation Guarantee contributions to your SMSF. The fund must have an active ESA registered with the ATO before your employer can locate and verify the fund. Employers generally have one to two months to action a choice of fund request.
Step 8: Ready to Start Investing
This essentially marks the completion of the "set up process" as the SMSF can start investing in assets once it has received funds into its bank account, subject to compliance considerations and investment restrictions under the law, investment strategy and SMSF Trust Deed. From this point, there are general ongoing compliance obligations to be met including, but not limited to:
| Obligation | Frequency | Responsible |
|---|---|---|
| Financial statements | Annual | Trustee / SMSF accountant |
| Independent audit | Annual | Approved SMSF auditor |
| SMSF annual return lodgement | Annual (31 Oct, extended via tax agent) | Trustee / registered tax agent |
| Investment strategy review | Annual (minimum) | Trustee |
| Trustee meeting minutes | As required | Trustee |
| SMSF supervisory levy ($259 in 2026) | Annual (via annual return) | Trustee |
| Record keeping | 5 yrs minimum (10 yrs for declarations & minutes) | Trustee |
Don't miss your annual return. A missed lodgement can cause the fund to lose its tax concessions and be reported to the ATO as non-complying, a consequence that is difficult and expensive to reverse.
Some Other General Considerations
There are a number of other important matters for SMSF trustees to be aware of, including but not limited to:
- Insurance: Unlike industry super funds, SMSFs do not provide default insurance cover. Trustees are required to consider whether life, total and permanent disability (TPD), and income protection cover should be held for each member within the fund or arranged separately.
- Sole purpose test: The fund must be maintained solely for the purpose of providing retirement benefits to members, or to their dependants in the event of a member's death. Breaching the sole purpose test is a serious offence under superannuation law.
- Access to super: Superannuation held in an SMSF is subject to the same preservation rules as any other super fund. Funds generally cannot be accessed until a member satisfies a condition of release, such as retirement after reaching preservation age or turning 65.
What Does It Cost to Set Up an SMSF?
| Cost Item | Estimated Range |
|---|---|
| Setup - individual trustee (once-off) | $800-$2,500† |
| Setup - corporate trustee (once-off, incl. ASIC $611 in 2026) | $1,500-$3,500† |
| ASIC annual review fee (corporate only) | $70/yr in 2026# |
| Annual audit | $350-$900/yr# |
| Annual accounting, management & administration | $3,309/yr (avg. $5,164)# |
| ATO supervisory levy | $259/yr in 2026# |
# ATO median figures sourced from the 2023-24 SMSF Annual Overview. ATO median (2023-24): audit $550/yr (avg. $651); management & admin $3,309/yr (avg. $5,164). The ATO combines accounting, audit, and administration into a single figure; separate benchmarks for each are not published.
† Industry range, not tracked by ATO. Figures are market-derived (industry sources, 2026).
We have a breakdown of our pricing on our pricing page.
How We Can Help
Setting up an SMSF does not have to be a complicated and stressful process. With Altitude SMSF Accounting, simply tell us you wish to establish an SMSF and we can help throughout the entire setup process, from trust deed preparation and corporate trustee establishment (if required) through to ATO registrations for ABN and TFN, and assistance with providing the necessary information to facilitate rollovers and contributions. We also provide ongoing compliance support to help keep your fund in order and avoid issues with the ATO. For further information or to proceed, get in touch for a free consultation to begin your journey.
Further Reading
- ATO: Setting Up an SMSF - Official guidance covering eligibility, trustee structure, and registration
- ATO: SMSF Administration and Reporting - Your ongoing obligations as a trustee
- ATO: Trustee Declaration (NAT 71089) - The declaration each new trustee must sign
- ATO: SMSF Education Products - Publications and checklists for setting up and running your fund
- Altitude: SMSF Contribution Caps for FY2027 - Understanding concessional and non-concessional caps once your fund is established
- Altitude: SMSF Administration Pricing - Our transparent, fixed-fee pricing for ongoing SMSF administration
This article has been prepared for general information purposes only and does not constitute financial, investment, legal or taxation advice. Altitude SMSF Accounting Pty Ltd does not hold an Australian Financial Services Licence (AFSL). SMSF establishment requirements and fees are subject to change. Always seek independent professional advice before establishing a self-managed superannuation fund.